Sunday, March 02, 2008

Obamanomenim

I don't do politics here but I can't let this pass. Obama is as much a cultural phenomenon as a political race.

Barack Obama came to town and delivered a wonderful speech a few weeks ago. In that speech he said exactly what his audience wanted to hear. Now I see his name and picture on the TV every time turn it on. I've read his positions and watched him speak.


There is no doubt he has run a nearly perfect campaign. He managed expectations early on, exceeding them by just enough for his candidacy to grow, without attracting too much attention. He has avoided making any mistakes. He is an impressive speaker, at ease in front of a crowd yet delivering his message powerfully.

He is now in the position that many people believe he will inevitably be the next president of the United States.


His swift rise in national politics can be compared to John F Kennedy's. Their charismatic personalities and speaking abilities are two of the obvious similarities. They are about the same age, served relative short senate careers. Both rose to national attention on their exposure at the previous Democratic Party National Convention.


Still I can't shake a feeling that he might be like Robert Redford's character in "The Way We Were".
"In a way he was like the country he lived in, Everything came to easily to him. But at least he knew it"
Kennedy had been tested in World War II. I can't find any similar trials in Obama's background.

I also have known a few charismatic people who seem to effortlessly move from place to place achieving every higher status without ever actually accomplishing much or ever having been tested.

Tuesday, February 26, 2008

The Appeal of the Appeal of the Property Taxes - The Last Dance

We had the hearing on Erroll Williams' appeal of my appeal of the incorrect appraisal of my property taxes today.

The appeal was held at the Homewood Suites in a meeting room on the second floor. I had been there before for a meeting. There was a sign in table and a person who checked for your hearing date and time. There was a fairly comfortable waiting area.

I got there early so I could observe a few of the hearings before mine. It was very informal but more formal than the hearings at the Super Dome. Everyone was sworn and the hearings recorded. Generally the Hearing Officer sat behind a table with a computer and apparently had access to the Internet to check things during the hearing. The Assessor or his (or her) representative was present as well. The typical hearing took fifteen or twenty minutes.

The first thing I learned was that you can download your appraisal from the Tax Commission New Orleans Appeals website. I didn't know that and I'm glad I didn't because it was wrong. It was so wrong that the Hearing Officer immediately said the appraisal was not valid. If I'd known that before, it would have worried me. The Tax Commission Appraisal included comparables nowhere near my house and outside my neighborhood, one more than a mile away.

I was able to locate 3 comparables on my block, one next door to my house in a few minutes on the Internet. The Hearing Office consulted a different database than I had and determined that my comparables were valid. I wonder how much the bungled appraisal cost?

Between the three of us we quickly arrived at an agreement. The Board of Review had for some reason decided to adjust my land value and split the value of the improvements and the land. I had requested that they keep the land value and simply adjust the improvements. Today we changed the land value back and raised the total value slightly from the Board of Review number which was slightly higher than our request. Everyone came away happy, I think.

The assessors seem to have collectively decided that maintaining consistency in land values is of overarching significance, even it the total value is what counts for taxes. It seem sto be a major point of contention as well.

I think its over. The Hearing Officer, the representative from the assessors office and I agreed on a number, $6,000 higher than the last number but within a reasonable range.

I don't think I'll have to go to Court.

This whole thing could have been worked out with the Assessor if there had been a concerted effort by the Assessor to meet with people during this process.

Now all I have to do is wait until April or May for the Tax Commission to act and then wait three or four months for the City to send me another revised bill.

Monday, February 25, 2008

FEMA Called


They were taking a survey. They wanted to know;

  1. Had the maintenance contractor contacted us about inspecting the trailer?
  2. Had the maintenance contractor asked us about maintenance of our trailer?
The answers are No and No. The Contractor leaves us monthly maintenance reports stuck to the door about every three months. They do come out when we call them, and check some stuff then.

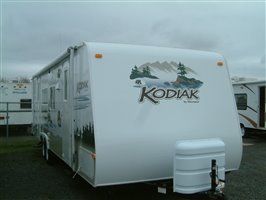
The trailer gnomes come by from time to time and do stuff, sometimes they paste more instructions to the side of the trailer. Sometimes they insulate our water supply.

Last week they duct taped a notice to our door warning us of Formgehyde. They want us to move, but they don't offer to test the trailer

Come to think of it I think my refer is broken. It recently occurred to me that it was supposed to run on either electricity or propane. The Electric part seems broken. If the propane tanks go empty, the Refer stops working, but if the Refer ran on electricity the tanks should last a very long time, since the only use would be for cooking and heating. We heat water with electricity.

Time to call the Maintenance Contractor.

Sunday, February 24, 2008

Whose Mortgage Crisis is it?

"Activists" are blaming the big bad bankers;
"The people who bought here thought they were living the American dream, but they could never afford the loans they were given," said Livia Villareal, counseling services director at the Greater Southwest Development Corp., a local non-profit."
I seem to recall a few years ago these same "activists" (or their cousins) were calling on lenders to make credit available to non-traditional borrowers. People who had been locked out of home ownership due to "economic" discrimination and "red-lining".

In 2003 during American Homeownership Month George W. Bush proclaimed,
Although a record number of Americans own their own homes, we continue to see a gap between the homeowner-ship rates of minorities and nonminorities. By a significant margin, minority families are less likely to own their own homes. Therefore, I have called upon the entire housing industry to join with my Administration to expand minority homeownership across the Nation. Our goal is to help at least 5.5 million minority families become homeowners by the end of this decade, and our Blueprint for the American Dream Partnership is taking bold steps to make this a reality.
The Current Home mortgage "crisis" was predictable and inevitable. I turned down a mortgage that was "too good to be true', because the eventual escalation of the payment was unsustainable.

Just to prove it's not a Republican Plot, here's a statement from Bill Clinton's White House Aug 1, 2000
Incentives for home ownership

There is no more crucial building block for a strong community and a promising future than a solid home.“ The Clinton Administration is dedicated to making the dream of homeownership a reality for all Americans. In 1995, the Administration, in partnership with 50 key public and private sector organizations, formed a National Homeownership Strategy with the goal of helping more Americans become homeowners.

Accomplishments include:
  • Lowering Interest Rates by Paying Off the National Debt.
  • Record Levels of Homeownership Assistance via 1.3 million loans from the Federal Housing Administration.
  • Helping Renters Buy Their First Home via homeownership vouchers for 50,000 families.
  • Providing Incentives to Save for a Home via Individual Development Accounts, providing incentives through federal matching funds for low-income families to save for a first home, higher education, or to start a new business.
None of the official sources mention the pressure put on lenders to offer credit to "non-traditional" borrowers, or to eliminate "red lining". Both of which could be easily taken as code words for reducing underwriting requirements.

These were not the primary means the mortgage market was subverted. The primary driver was the acquiescence of Ginnie Mae and Freddie Mac indicating to the markets that writing new risky types of mortgages was backed by the US Government. The Lenders, insulated from the risk of default and benefiting from the transaction fees, forged ahead.

In effect risk and reward became disconnected.

There were ways to increase homeownership by offering less risky, nontraditional mortgages, like shared equity mortgages or other suggestions put forward by Bernard Condon of Forbes Magazine.

We seem to have discarded the lessons of the past for the allure of something for nothing. Many of the people who are now in dire straits bought too much house for their income by any traditional standard. This artificial demand caused the housing bubble, artificially high housing prices and rampant speculation.

The borrowers are not entirely to blame, in many ways they are victims. They had many helpers. The Real Estate Industry chasing ever bigger commissions, the Loan Origination Industry chasing transaction fees and the equities markets looking at short term gains over long term stability. Still if something is too good to be true, it usually is.

The difference between the lenders and the borrowers, is the borrowers were not as well equipped to evaluate the risk as the lenders. But the lenders had a backstop, Fannie Mae, Gennie Mae, the VHA and the VA who were all willing to let the train roll on in the name of increasing homeownership, however transitory. Everyone hoped that the reckoning they all knew was coming would happen to the next guy.

Tuesday, February 19, 2008

Riddle me this!

I've been looking at this map Maitri made and these FEMA maps.

Jim Carrey as the Riddler

In my neighborhood existing grade elevations are between three and six feet above sea level. We are required to build at least three feet above grade, resulting in a minimum floor elevation of six feet.

Immediately across the street in Gentilly the grade elevation is generally negative one foot and lower. They are required to build 3 feet above grade or one half food below sea level, whichever is higher. That makes the floor elevation a maximum of two feet.

In Lakeview the average grade elevations are negative three to six feet. There people are required to build three feet above grade or two and one half feet below sea level. That results in a floor elevation of negative two and one half feet.

There is no significant difference in the potential flooding from any of the most likely mechanisms for catastrophic flooding, breach of the levees or over topping (which would likely lead to breaches if it were substantial enough).

Frank Gorshin as the Riddler

Does this makes sense?

I wonder who thinks up this stuff?

I realize I have generalized the conditions to illustrate the principle.